Your Medicare, Checked Line by Line
Bring the notices, the pill bottles and the names of the doctors you trust. Held side by side, they show which plan really fits.
Start your reviewThree Piles That Usually Land on the Table

The mail pile
Each notice is opened, sorted and explained in turn.

The pill bottles
Each pill is checked against every plan's drug list.

The doctor names
Your current doctors are looked up in every network.
Medicare Explained From Your Side of the Table
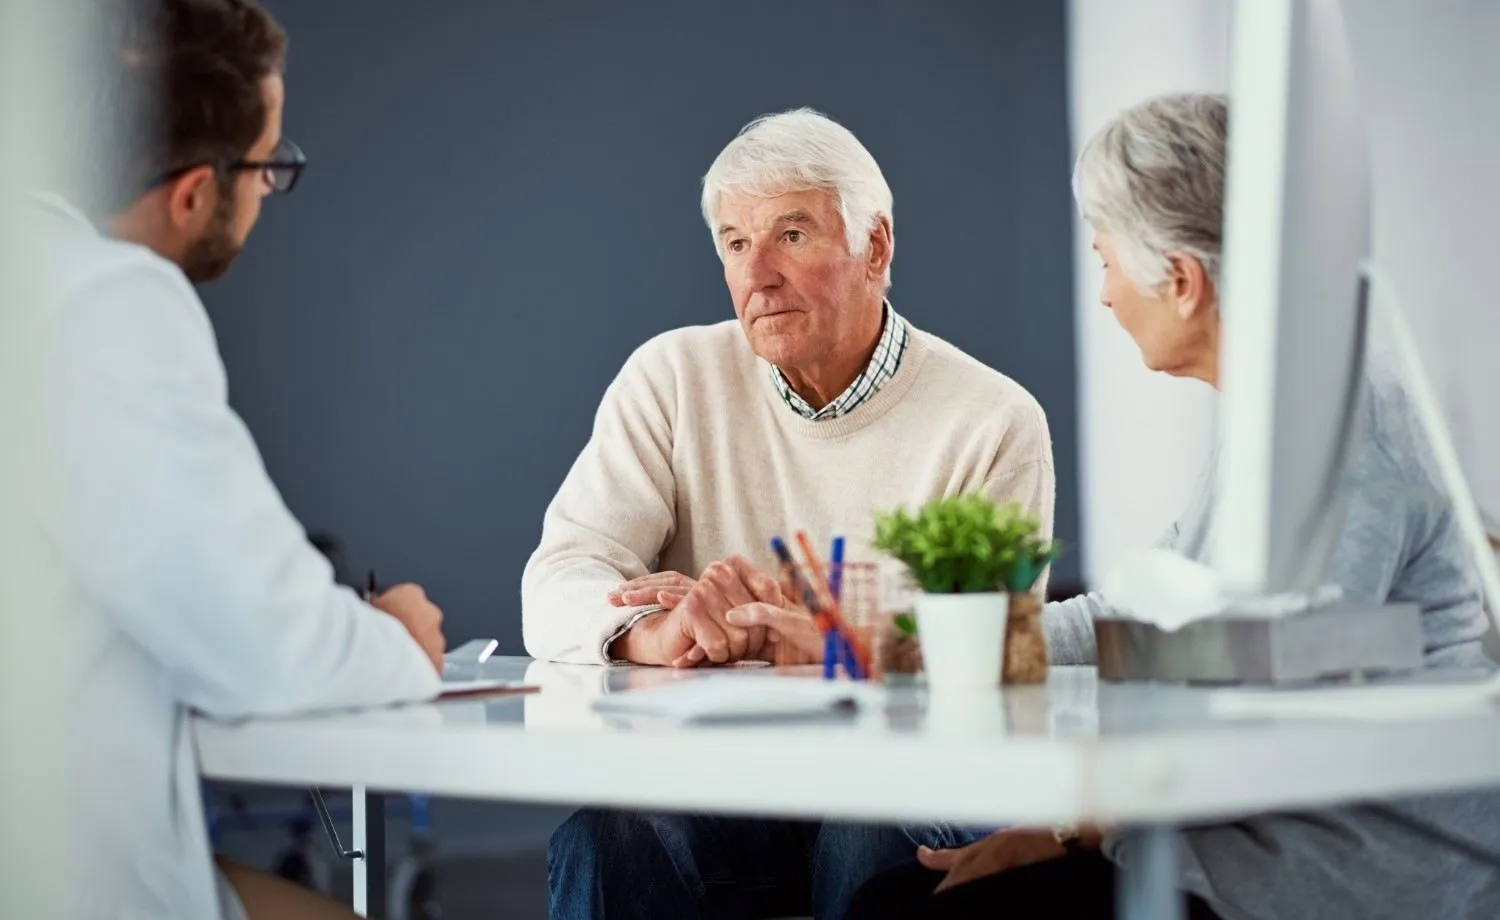
A brochure makes every plan look fine. Next to your pharmacy receipts and your specialist's name, the picture changes, and that is the view I work from.
Your last year counts
Your visits, refills and bills set the measure for any plan.
Ask whenever you like
Send a question whenever a letter arrives or a rule changes.
Four Decisions Hiding Inside One Medicare Card
When to sign up
Your first window opens before your birthday month and shuts after it. Missing it can add a penalty that does not go away.
Two kinds of plan
The government runs one and accepts any doctor who takes it. The second is a private plan with its own network and extras.
Drug coverage
Part D plans price the very same pill differently. Matching your list to a plan's tiers is where most of the saving hides.
Filling the gaps
A Medigap policy picks up costs that Original Medicare leaves behind, and the letter you go for sets how much it will pay.
Words From People Who Sat Down With Their Paperwork
Questions That Come Up at Nearly Every Table
No. If your plan still fits, you can leave it alone. A quick yearly check is still worth doing, because plans change their drug lists, networks and prices, and the yearly notice tells you exactly what moved.
Coverage from a current employer can let you delay some parts of Medicare without a penalty. The size of the employer and the type of coverage both matter, so it is worth checking before your birthday month.
Often, yes. With Original Medicare, any doctor who accepts it can see you. With an Advantage plan, it depends on the network, so every doctor you depend on is looked up carefully before any plan gets chosen.
No. Going through your details only shows you how the plans compare against one another. If you decide to enroll, that step stays yours to take, and it can proceed with or without further assistance from me.
Medigap sits beside Original Medicare and pays a share of what it leaves behind. An Advantage plan swaps it for a private version of the coverage, often adding dental or eye care and setting its own network.